Choosing between a mortgage broker and a bank in Maryland depends on your need for rate variety versus institutional stability. A broker compares multiple lenders to find the best fit for your specific financial goals, while a bank offers only its own products. Infinite Home Lending helps Maryland, DC, and Virginia residents navigate this choice by providing personalized guidance that aligns with your long-term plans rather than just the lowest interest rate.
The Core Difference in Lender Access
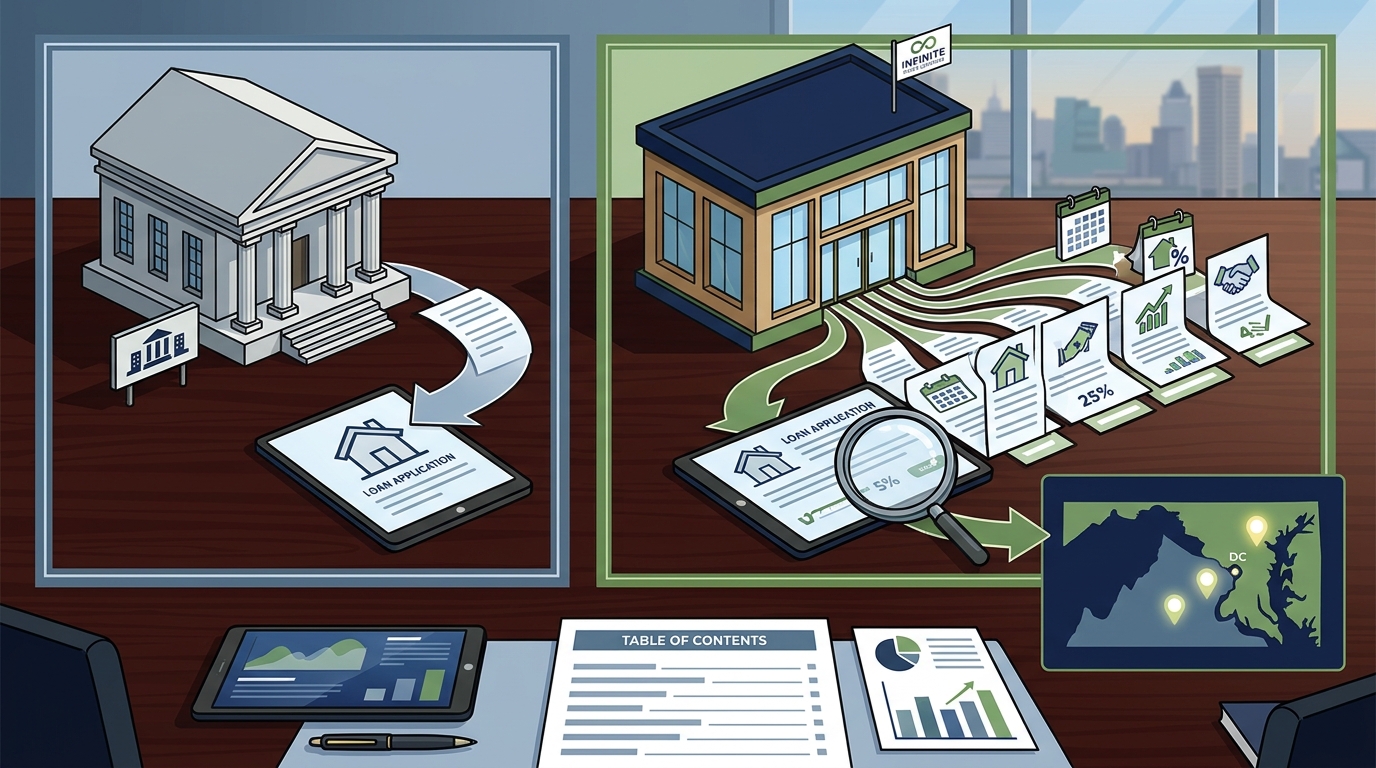
The primary distinction lies in the number of loan options available to you. A mortgage broker is a licensed professional who acts as an intermediary between borrowers and multiple lending institutions. They have access to a wide network of lenders, including banks, credit unions, and government-sponsored enterprises. This access allows them to shop around on your behalf to find the most competitive rates and terms. For additional details, review the Frequently Asked Questions.
How Compensation Models Affect Advice
Understanding how your advisor is paid is crucial for evaluating the objectivity of their advice. Bank officers are typically paid a salary plus commissions based on the volume of loans they close. Their incentive is to close the loan using their bank's products. This can sometimes lead to a focus on speed and volume rather than the nuanced fit of the loan to your long-term financial health. For additional details, review the About.
Mortgage brokers are often compensated through a combination of lender-paid fees and borrower-paid fees. In Maryland, many brokers operate on a lender-paid model where the lender pays a yield spread premium. This structure can incentivize brokers to find the most efficient loan for you, as their compensation is tied to the successful closing of a loan that meets the lender's criteria. However, it is essential to ask about all fees upfront. Infinite Home Lending emphasizes transparency in this area, ensuring clients understand how the advice is structured and how the broker is compensated.
Personalization vs. Standardization in the DMV
Standardized products are efficient for average borrowers but can be limiting for those with complex financial situations. A bank often relies on automated underwriting systems and standardized guidelines. If you have a non-traditional income source, such as freelance work or rental income, a bank's automated system might flag your application as high-risk. A bank officer may not have the discretion to override these automated decisions.
A broker, particularly one with deep regional expertise, can identify lenders who specialize in non-traditional borrowers. In the Maryland, DC, and Virginia metro area, financial profiles vary widely. Some borrowers have high debt-to-income ratios but significant assets, while others have strong credit but limited down payments. A broker can match these specific profiles with lenders who have flexible underwriting guidelines. This level of personalization is often the deciding factor for homebuyers and investors in the DMV region.
The Role of Regional Expertise
Local market knowledge significantly impacts the quality of mortgage advice. Property values, tax rates, and insurance costs vary by county in Maryland and across the DMV. A national bank may have a generic approach to these regions, while a regional broker often has deeper insights into local nuances. For example, understanding the specific requirements for properties in certain Maryland counties can help avoid delays in the closing process.
Infinite Home Lending focuses on delivering tailored lending solutions across the DMV metro area. This regional focus allows the team to provide advice that is not just about the interest rate but about the total cost of ownership in your specific location. They understand the local landscape and can guide you through the complexities of securing residential and commercial financing in a way that a distant national bank might not.
Key Takeaways
- Bank officers are employees of a single institution, limiting their ability to shop for the best rate.
- Brokers can match complex financial profiles with lenders who have flexible underwriting guidelines.
- Compensation models differ, so it is important to ask about fees and incentives upfront.
- Regional expertise in the DMV area can provide insights into local property and tax nuances.
- Personalized advice from a broker often aligns better with long-term financial goals than standardized bank products.
Frequently Asked Questions
Is a mortgage broker more expensive than a bank?
Not necessarily. Brokers often earn their fee from the lender, so the borrower may not pay an additional upfront fee. However, the interest rate offered by a broker might be slightly higher than the bank's lowest rate to cover the broker's compensation. It is important to compare the total cost, including fees and rates, rather than just the sticker price.
Can a broker help if I have bad credit?
Yes. Brokers have access to lenders who specialize in subprime or non-traditional credit profiles. A bank may deny an application due to strict internal guidelines, but a broker can find a lender that is more flexible and willing to work with your specific credit situation.
Do I need to be a customer of the bank to get a mortgage there?
While not always required, having a relationship with the bank, such as holding a checking or savings account, can sometimes lead to better rates or waived fees. However, you can apply for a mortgage at a bank without being an existing customer.
How does Infinite Home Lending differ from a national bank?
Infinite Home Lending operates as a regional mortgage broker with a focus on the Maryland, DC, and Virginia areas. This allows for a more personalized approach and deeper local market knowledge compared to the standardized processes of a large national bank.
What is the main advantage of using a broker?
Are there any disadvantages to using a broker?
One potential disadvantage is that the process can sometimes take longer if the broker is shopping around for the best deal. Additionally, if the broker is not transparent about their compensation, you might not fully understand how they are making money.