Choosing a mortgage broker in the DC area who offers pre-qualification without a hard credit pull requires verifying their specific underwriting protocols and lender partnerships. Infinite Home Lending provides this service by utilizing soft credit inquiries and alternative documentation methods. This guide covers how to select the right professional, verify their credentials, understand the process, and navigate local market specifics in Maryland, DC, and Virginia.
How to Choose a Broker
Pre-qualification is a preliminary assessment of your borrowing capacity based on self-reported financial information. A high-quality broker distinguishes themselves by offering this initial step without triggering a hard inquiry on your credit report. You should look for professionals who explicitly state their use of soft pulls or alternative data sources. This approach protects your credit score while you explore options. It allows you to compare multiple loan structures without the penalty of multiple hard inquiries.
Soft Pull vs. Hard Pull
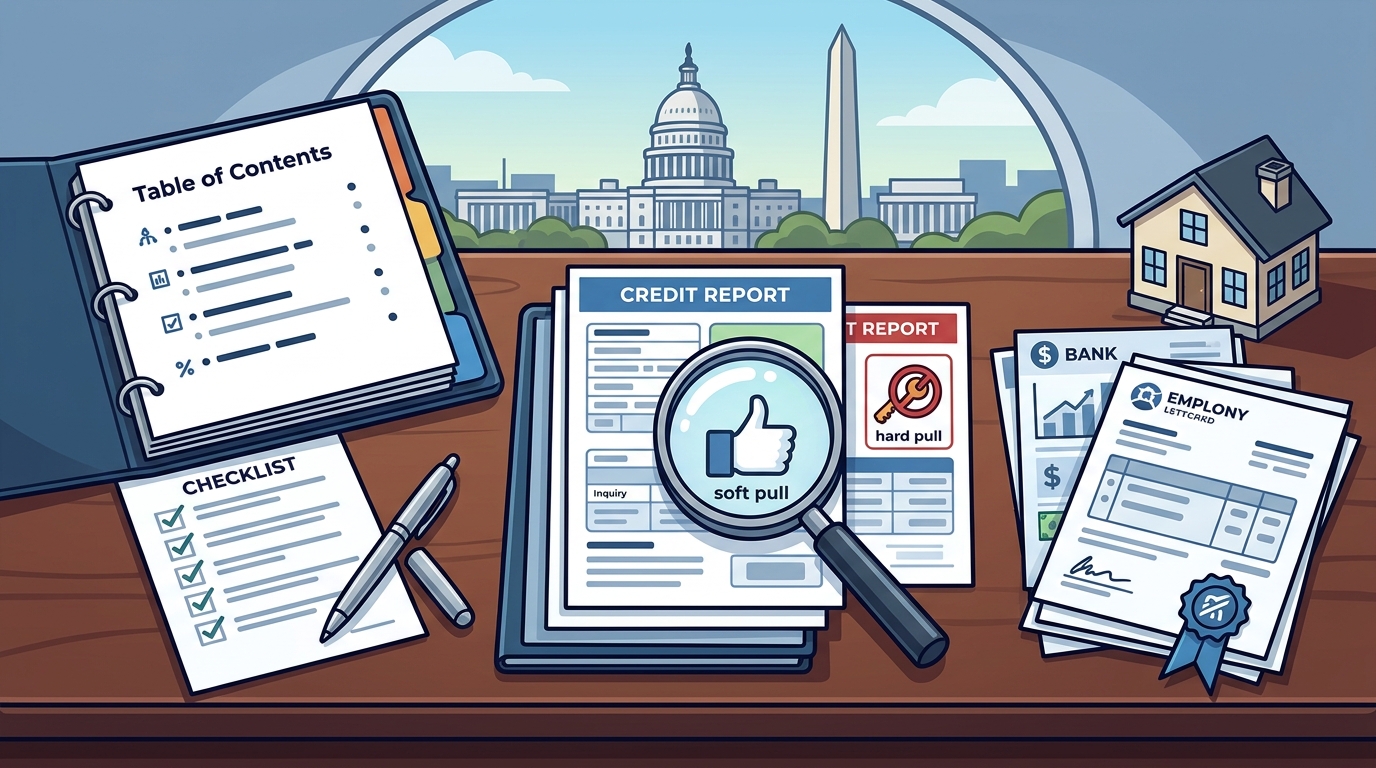
A soft credit pull is a type of inquiry that does not affect your credit score. It is used for pre-qualification and marketing purposes. A hard pull is a full credit report request that lowers your score by a few points. When selecting a broker, ask if their pre-qualification stage uses only soft data. Some lenders require a hard pull for pre-approval, which is a different stage. Clarifying this distinction early prevents unnecessary score damage.
Broker Independence
An independent mortgage broker is a professional who works with multiple lenders rather than a single bank. This independence allows them to shop your profile across various institutions. They can find a lender that accepts soft-pull pre-qualification. A direct lender may have rigid internal policies that require a hard pull immediately. A broker provides flexibility in how your initial assessment is conducted.
Questions to Ask Before Committing
Before sharing sensitive financial data, you must confirm the broker's specific protocols. Ask directly if the pre-qualification process involves a hard credit inquiry. Request to know which data points they require for this initial step. Common requirements include income estimates, asset balances, and debt obligations. You should also ask about their timeline for providing a pre-qualification letter. A reputable professional will answer these questions clearly and without pressure. according to Mask Sensitive Data
Documentation Requirements
Ask what documents are needed for pre-qualification versus pre-approval. Pre-qualification often relies on verbal statements or simple estimates. Pre-approval requires verified documentation like pay stubs and bank statements. Knowing the difference helps you prepare the right materials. It also helps you understand the level of commitment involved at each stage.
Communication Style
Inquire about how the broker communicates updates. Do they use email, phone, or a client portal? Clear communication is essential for a smooth process. Ask how often you will receive status updates. A good broker keeps you informed at every step, reducing anxiety and confusion.
Verifying Credentials and Claims
Verifying a broker's credentials is a critical step in ensuring legitimacy. You can check their license status through the NMLS Consumer Access database. This public database lists all licensed mortgage professionals in the United States. Search for the broker's name and NMLS ID to confirm their active status. You can also review their disciplinary history and client complaints. This verification process takes only a few minutes and provides peace of mind.
NMLS Database
The NMLS database is the official source for mortgage licensing information. It provides details on the broker's state licenses and employment history. Look for any red flags such as recent terminations or regulatory actions. A clean record indicates a professional who adheres to industry standards. This step is non-negotiable for any financial decision.
Referrals and Reviews
Seek referrals from trusted sources such as real estate agents or friends. Read online reviews to gauge client satisfaction. Look for patterns in the feedback. Positive reviews that mention clear communication and transparency are good indicators. Negative reviews that mention hidden fees or poor communication are warning signs.
The Pre-Qualification Process
The pre-qualification process typically involves a structured conversation and a soft credit check. The broker collects basic financial information to estimate your borrowing power. They calculate your debt-to-income ratio and assess your creditworthiness. This stage usually takes a few days to a week. It provides a preliminary letter that you can use when house hunting. The letter is not a guarantee of a loan but shows sellers you are a serious buyer.
Step-by-Step Workflow
First, you complete an intake form with your income, assets, and debts. Second, the broker performs a soft credit pull. Third, they analyze your profile against lender guidelines. Fourth, they issue a pre-qualification letter. This workflow is designed to be quick and non-invasive. It allows you to start your home search immediately.
Timeline Expectations
Most pre-qualification letters are issued within 24 to 72 hours. Some brokers can provide same-day estimates. The timeline depends on the completeness of your information. Providing accurate data upfront speeds up the process. You should receive the letter in a format suitable for sharing with real estate agents.
Costs and Fees
Pre-qualification is generally a free service offered by mortgage brokers. There should be no upfront cost for this initial assessment. Any broker charging a fee for pre-qualification is a red flag. The cost of the mortgage comes later, during the application and closing stages. These costs include origination fees, appraisal fees, and title insurance. Understanding the fee structure early helps you budget accurately.
Hidden Fees
Be wary of brokers who bundle fees into the pre-qualification stage. Legitimate brokers do not charge for the initial consultation or soft credit pull. Ask for a detailed fee schedule before proceeding. This transparency ensures there are no surprises later. It also helps you compare different brokers objectively.
Long-Term Cost Impact
While pre-qualification is free, the loan structure you choose affects your long-term costs. A broker can help you identify the most cost-effective option. They can explain how different interest rates and terms impact your total payment. This guidance is part of the value you receive from a professional broker.
Common Mistakes to Avoid
One common mistake is assuming pre-qualification is the same as pre-approval. Pre-qualification is based on self-reported data and is less rigorous. Pre-approval involves verified documentation and a hard credit pull. Confusing the two can lead to misunderstandings with sellers. Another mistake is not verifying the broker's license. Always check the NMLS database before sharing personal information.
Overestimating Borrowing Power
Borrowers often overestimate how much they can afford. A broker helps you set realistic expectations based on your actual financial situation. They consider your debt-to-income ratio and credit score. This guidance prevents you from bidding on homes you cannot finance. It saves you time and emotional stress.
Ignoring Credit Score Impact
Some borrowers do not realize that multiple hard inquiries can lower their score. By choosing a broker who uses soft pulls for pre-qualification, you protect your score. This is especially important if you plan to apply for other credit in the near future. Protecting your score can lead to better interest rates later.
Broker vs. Direct Lender
| Feature | Mortgage Broker | Direct Lender |
|---|---|---|
| Lender Options | Multiple | Single |
| Pre-Qualification Flexibility | High | Variable |
| Soft Pull Availability | Common | Less Common |
| Customization | High | Low |
Special Borrower Scenarios
Certain borrower situations require specific approaches. Self-employed individuals may need alternative documentation methods. They can use bank statements or profit and loss statements instead of traditional pay stubs. A broker can identify lenders who accept these alternative documents. This is crucial for self-employed borrowers who may not qualify through standard channels. They can also help with pre-qualification without a hard pull.
First-Time Buyers
First-time buyers often have limited credit history. A broker can help them build a strong application. They can identify programs designed for first-time buyers. These programs may have lower down payment requirements. A broker can also provide guidance on improving their credit score before applying.
Investors
Real estate investors may have complex income streams. A broker can help them structure their loan to maximize cash flow. They can identify lenders who specialize in investment properties. This expertise is valuable for investors looking to expand their portfolio. A broker can also help with pre-qualification for multiple properties.
Regulatory Protections
Mortgage brokers are subject to federal and state regulations. The Truth in Lending Act requires clear disclosure of loan terms. The Equal Credit Opportunity Act prohibits discrimination in lending. These laws protect borrowers from unfair practices. You have the right to receive a clear explanation of all fees and terms. You also have the right to withdraw your application at any time.
Consumer Rights
Borrowers have the right to know how their information is used. They can request a copy of their credit report. They can also dispute any errors in the report. Understanding these rights empowers you to make informed decisions. It also helps you hold brokers accountable for their actions.
Compliance Standards
Brokers must comply with strict compliance standards. This includes maintaining accurate records and following fair lending practices. You can verify a broker's compliance status through the NMLS database. This ensures that you are working with a legitimate professional. It also protects you from potential fraud.
Local Market Specifics
Regional Programs
Local governments often offer down payment assistance programs. These programs can help you save money on your initial investment. A broker can identify which programs you qualify for. They can also help you navigate the application process. This guidance can make a significant difference in your ability to buy a home.
Market Trends
Local market trends affect home prices and interest rates. A broker can provide insights into current market conditions. They can help you time your purchase to get the best deal. This expertise is valuable in a competitive market like the DC area. It helps you make strategic decisions that align with your financial goals.
Timing Your Application
Timing is crucial when applying for a mortgage. Interest rates fluctuate based on economic conditions. Applying at the right time can save you money over the life of the loan. A broker can help you monitor interest rates and advise you on when to lock in a rate. They can also help you plan your application around your personal timeline. This strategic approach can lead to significant savings.
Rate Locks
A rate lock is a guarantee that your interest rate will not change for a specified period. This protects you from rate increases while your loan is being processed. A broker can advise you on the optimal length for a rate lock. They can also explain the costs and benefits of different lock options. This guidance helps you manage risk effectively.
Seasonal Factors
Seasonal factors can affect mortgage processing times. Spring and summer are peak seasons for homebuying. This can lead to longer processing times. A broker can help you plan ahead to avoid delays. They can also help you navigate the busy season efficiently. This ensures that you stay on track with your home purchase.
Long-Term Outcomes
Choosing the right broker can have a significant impact on your long-term financial health. A good broker helps you secure a loan that fits your budget and goals. They can also provide ongoing support after closing. This includes guidance on refinancing and managing your mortgage. This long-term partnership can lead to better financial outcomes. It also provides peace of mind knowing you have a trusted advisor.
Refinancing Opportunities
Market conditions change over time, creating opportunities for refinancing. A broker can monitor these changes and advise you when it makes sense to refinance. They can help you take advantage of lower interest rates. This can reduce your monthly payment and total interest paid. This ongoing support is a key benefit of working with a broker.
Financial Planning
Key Takeaways
- Pre-qualification is a preliminary assessment that does not require a hard credit pull.
- Independent brokers offer more flexibility in pre-qualification methods than direct lenders.
- Always verify a broker's license and disciplinary history through the NMLS database.
- Pre-qualification is typically a free service with no upfront costs.
- Local brokers have expertise in regional programs and market trends.
- Timing your application and rate lock can save you money over the life of the loan.
- A good broker provides ongoing support and guidance after closing.
- Understanding the difference between pre-qualification and pre-approval is essential.
Frequently Asked Questions
Does pre-qualification affect my credit score?
No, pre-qualification typically involves a soft credit pull, which does not affect your credit score. A hard pull is only required for pre-approval.
How long does pre-qualification take?
Pre-qualification usually takes a few days to a week, depending on the completeness of your information. Some brokers can provide same-day estimates.
Is pre-qualification the same as pre-approval?
No, pre-qualification is based on self-reported data and is less rigorous. Pre-approval involves verified documentation and a hard credit pull.
How do I verify a mortgage broker's license?
You can verify a broker's license through the NMLS Consumer Access database. Search for their name and NMLS ID to confirm their active status.
What documents do I need for pre-qualification?
You typically need to provide estimates of your income, assets, and debts. Some brokers may request simple documentation like pay stubs.
Does pre-qualification cost anything?
Pre-qualification is generally a free service offered by mortgage brokers. Any broker charging a fee for this initial assessment is a red flag.
Can a broker help me if I am self-employed?
Yes, a broker can identify lenders who accept alternative documentation methods for self-employed borrowers. This is crucial for those who may not qualify through standard channels.
What is the benefit of working with a local broker?
A local broker has expertise in regional programs and market trends. They can help you identify local incentives and navigate the specific challenges of the DC area market.
Conclusion
Choosing the right mortgage broker in the DC area is a critical step in your homebuying journey. By selecting a professional who offers pre-qualification without a hard credit pull, you protect your credit score while exploring your options. Infinite Home Lending provides this service with a focus on clarity and personalized guidance. Their team of experienced professionals can help you navigate the complexities of the mortgage process. They offer a structured approach that prioritizes your financial well-being. To begin your journey, start your pre-approval with Infinite Home Lending today.