7 Ways to Get Pre-Qualified for a Mortgage Without Damaging Your Credit Score
Protecting your credit score is a critical first step in the homebuying journey. Many borrowers fear that checking their eligibility will lower their score, but this is a common misconception. Infinite Home Lending helps clients in Maryland, DC, and Virginia navigate this process safely. By using soft credit inquiries and strategic planning, you can assess your buying power without negative consequences.
1. Use a Soft Credit Inquiry
A soft inquiry does not affect your credit score. A soft credit inquiry is a type of credit check that allows a lender to view your credit history without impacting your score. This method is standard for pre-qualification. It lets you see if you qualify for a loan based on your current financial standing. Infinite Home Lending utilizes soft pulls to give you an initial idea of your loan options. according to Send Us a
2. Gather Financial Documents in Advance
Complete documentation speeds up the process and reduces the need for repeated checks. Having your income, assets, and debts organized helps the lender verify your information quickly. This preparation minimizes the chance of delays or additional inquiries. It ensures that the pre-qualification is based on accurate and current data. You should collect pay stubs, tax returns, and bank statements before starting.
3. Limit Hard Inquiries to a Short Window
Multiple hard inquiries within a short period may count as one. A hard credit inquiry is a check that can lower your score by a few points. However, credit scoring models often group mortgage inquiries made within a 14 to 45-day window as a single event. This allows you to shop for the best rate without significant damage. You should aim to complete your rate shopping within this specific timeframe.
4. Check Your Credit Report for Errors
Correcting errors ensures your score reflects your true financial health. A credit report is a detailed record of your credit history. Errors on this report can artificially lower your score. You can request a free report from major credit bureaus to review your history. If you find inaccuracies, you can dispute them to have your score corrected. This step is crucial before any formal application.
5. Avoid New Credit Applications
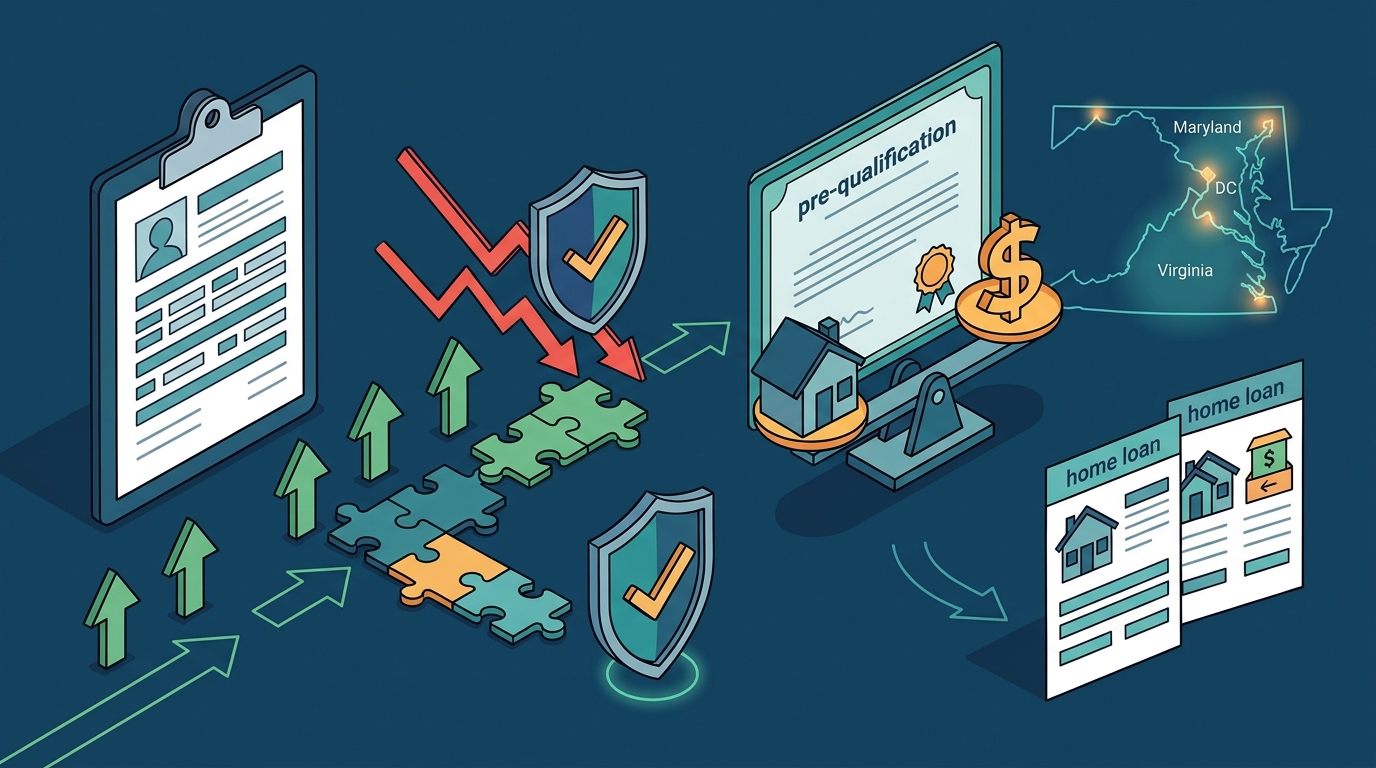
Opening new accounts can lower your average account age and increase debt. Applying for a new credit card or auto loan triggers a hard inquiry. It also increases your total debt, which can affect your debt-to-income ratio. Lenders look at this ratio to determine your ability to repay a mortgage. It is best to pause new credit applications until after you close on your home.
6. Use Mortgage Calculators for Initial Estimates
7. Consult a Local Mortgage Broker
Local expertise helps you navigate regional lending nuances safely. A mortgage broker is a professional who helps you find the best loan from various lenders. They understand the specific requirements in the DMV area. They can guide you through the pre-qualification process using soft inquiries. This personalized advice ensures you are prepared for the next steps.
Choosing the Right Approach
Select the method that best fits your current financial readiness. If you are just exploring, start with calculators and soft inquiries. If you are ready to buy, gather documents and consult a broker. This strategic approach protects your credit while moving you forward.
Frequently Asked Questions
Does a pre-qualification check my credit score?
How many hard inquiries can I have for a mortgage?
You can have multiple hard inquiries within a short window. Credit scoring models often group these into a single inquiry if they occur within 14 to 45 days.
What is the difference between pre-qualification and pre-approval?
Can I get pre-qualified without a credit check?
Yes, you can use online calculators for a rough estimate. However, a formal pre-qualification from a lender usually involves a soft credit check.
How long does a hard inquiry stay on my credit report?
A hard inquiry stays on your credit report for two years. However, it only affects your score significantly for the first 12 months.
Where can I start a mortgage pre-qualification in Bethesda?
You can start by contacting a local mortgage broker. Infinite Home Lending serves the Bethesda area and can guide you through the process.