Choosing the right financing partner in the Washington, DC, metropolitan area requires more than comparing headline interest rates. A mortgage broker is a licensed professional who connects borrowers with multiple lenders to find the best loan structure for their specific financial situation. In the competitive DMV market, this multi-lender access and strategic guidance can significantly impact your total cost of ownership and long-term financial flexibility.
1. Access to Multiple Lender Networks
Brokers provide a wider menu of loan products than a single bank branch. Independent mortgage brokers are not tied to one institution, allowing them to shop your profile across various lenders. This competition often results in more competitive pricing and terms that a single lender might not offer. For borrowers in the DC area, this access is crucial for finding a loan that fits both your budget and your timeline.
2. Expert Navigation of Local Regulations
Local expertise helps you avoid compliance pitfalls in the DMV region. The District of Columbia has specific licensing and operational requirements for mortgage professionals, as outlined in the D.C. Code. A local broker understands these nuances, including transfer taxes and specific underwriting guidelines for properties in Maryland, Virginia, and DC. This knowledge ensures your application is structured correctly from the start, reducing the risk of delays or rejections.
3. Personalized Loan Structuring
Strategic structuring aligns your loan with your broader financial goals. A mortgage broker is a financial advisor who looks beyond the monthly payment to understand your income stability, credit profile, and future plans. Whether you are a first-time buyer in Bethesda or an investor in Arlington, a broker can recommend structures that optimize your cash flow. This approach ensures the loan supports your life, rather than just meeting a minimum qualification threshold.
4. Simplified Documentation and Processing
Professional guidance streamlines the most complex parts of the application. Mortgage applications require extensive documentation, including tax returns, bank statements, and proof of income. A broker manages this process, telling you exactly what is needed and how to present it to underwriters. This reduces the back-and-forth that often slows down closings, which is particularly valuable in the fast-moving DC housing market. according to Mortgage Brokers
5. Objective Comparison of Loan Options
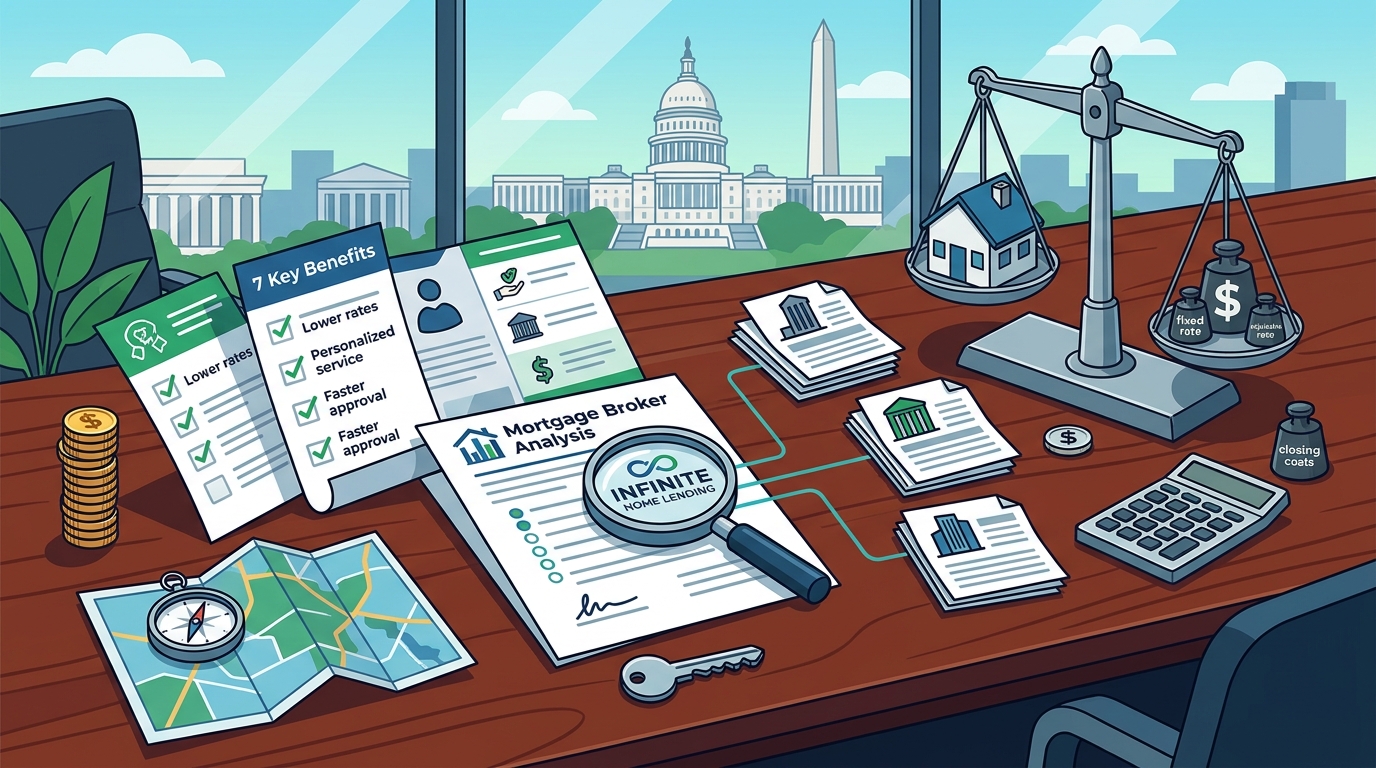
Neutral advice helps you weigh the true cost of different loan types. Because brokers work with multiple lenders, they can provide an objective comparison of conventional, FHA, and VA loan options. They can explain the trade-offs between upfront costs, mortgage insurance, and interest rates without the bias of a single lender's product menu. This clarity allows you to make an informed decision based on your specific financial data.
6. Advocacy During Underwriting
Experienced brokers act as your advocate when issues arise. If an underwriter has questions about your credit history or income, a broker can often provide context or additional documentation to resolve the issue. They understand the underwriting guidelines of various lenders and can navigate exceptions or compensating factors. This advocacy can be the difference between a loan being approved and a deal falling through.
7. Long-Term Financial Partnership
Building a relationship with a broker supports future financial moves. Your needs will change over time, whether you are refinancing, accessing home equity, or purchasing an investment property. A local mortgage broker is a resource for these future decisions, providing continuity and insight into how your current loan structure affects your options down the road. This long-term perspective is a key benefit of working with a specialized regional firm.
Choosing the Right Broker for Your Needs
When selecting a mortgage broker in the DC area, prioritize firms that offer transparent communication and a clear process. Look for a team that emphasizes education and strategy over high-pressure sales tactics. Verify their licensing through the NMLS Consumer Access database to ensure they are properly registered in your state. A good broker will make you feel informed and confident at every step of the journey.
Frequently Asked Questions
How much does it cost to use a mortgage broker in DC?
Broker fees are typically paid by the lenders they work with, so there is often no direct cost to the borrower. However, the loan terms may reflect the broker's compensation. It is important to ask for a clear breakdown of all fees and how they are structured before applying.
Is a mortgage broker the same as a loan officer?
No, a loan officer works for a single lender and can only offer that lender's products. A mortgage broker is an independent professional who can shop your application across multiple lenders to find the best fit for your needs.
Do I need a broker if I have a good credit score?
Even with excellent credit, a broker can help you find the most competitive rate and the best loan structure for your specific situation. They can also provide guidance on local market conditions and tax implications that a single lender might overlook. according to 26 1114 Prohibited
How long does the mortgage process take with a broker?
The timeline depends on the lender and the complexity of your application, but a broker can help streamline the process by ensuring all documentation is complete and accurate. In the DC area, the process typically takes 30 to 45 days from application to closing.
Can a broker help with investment properties in the DMV?
Yes, many brokers specialize in investment financing, including DSCR (Debt Service Coverage Ratio) loans and bank statement programs. These options are often more flexible for investors than traditional owner-occupied loans.